Housing Market Forecasts: a Light at the End of the Tunnel
Furley Page
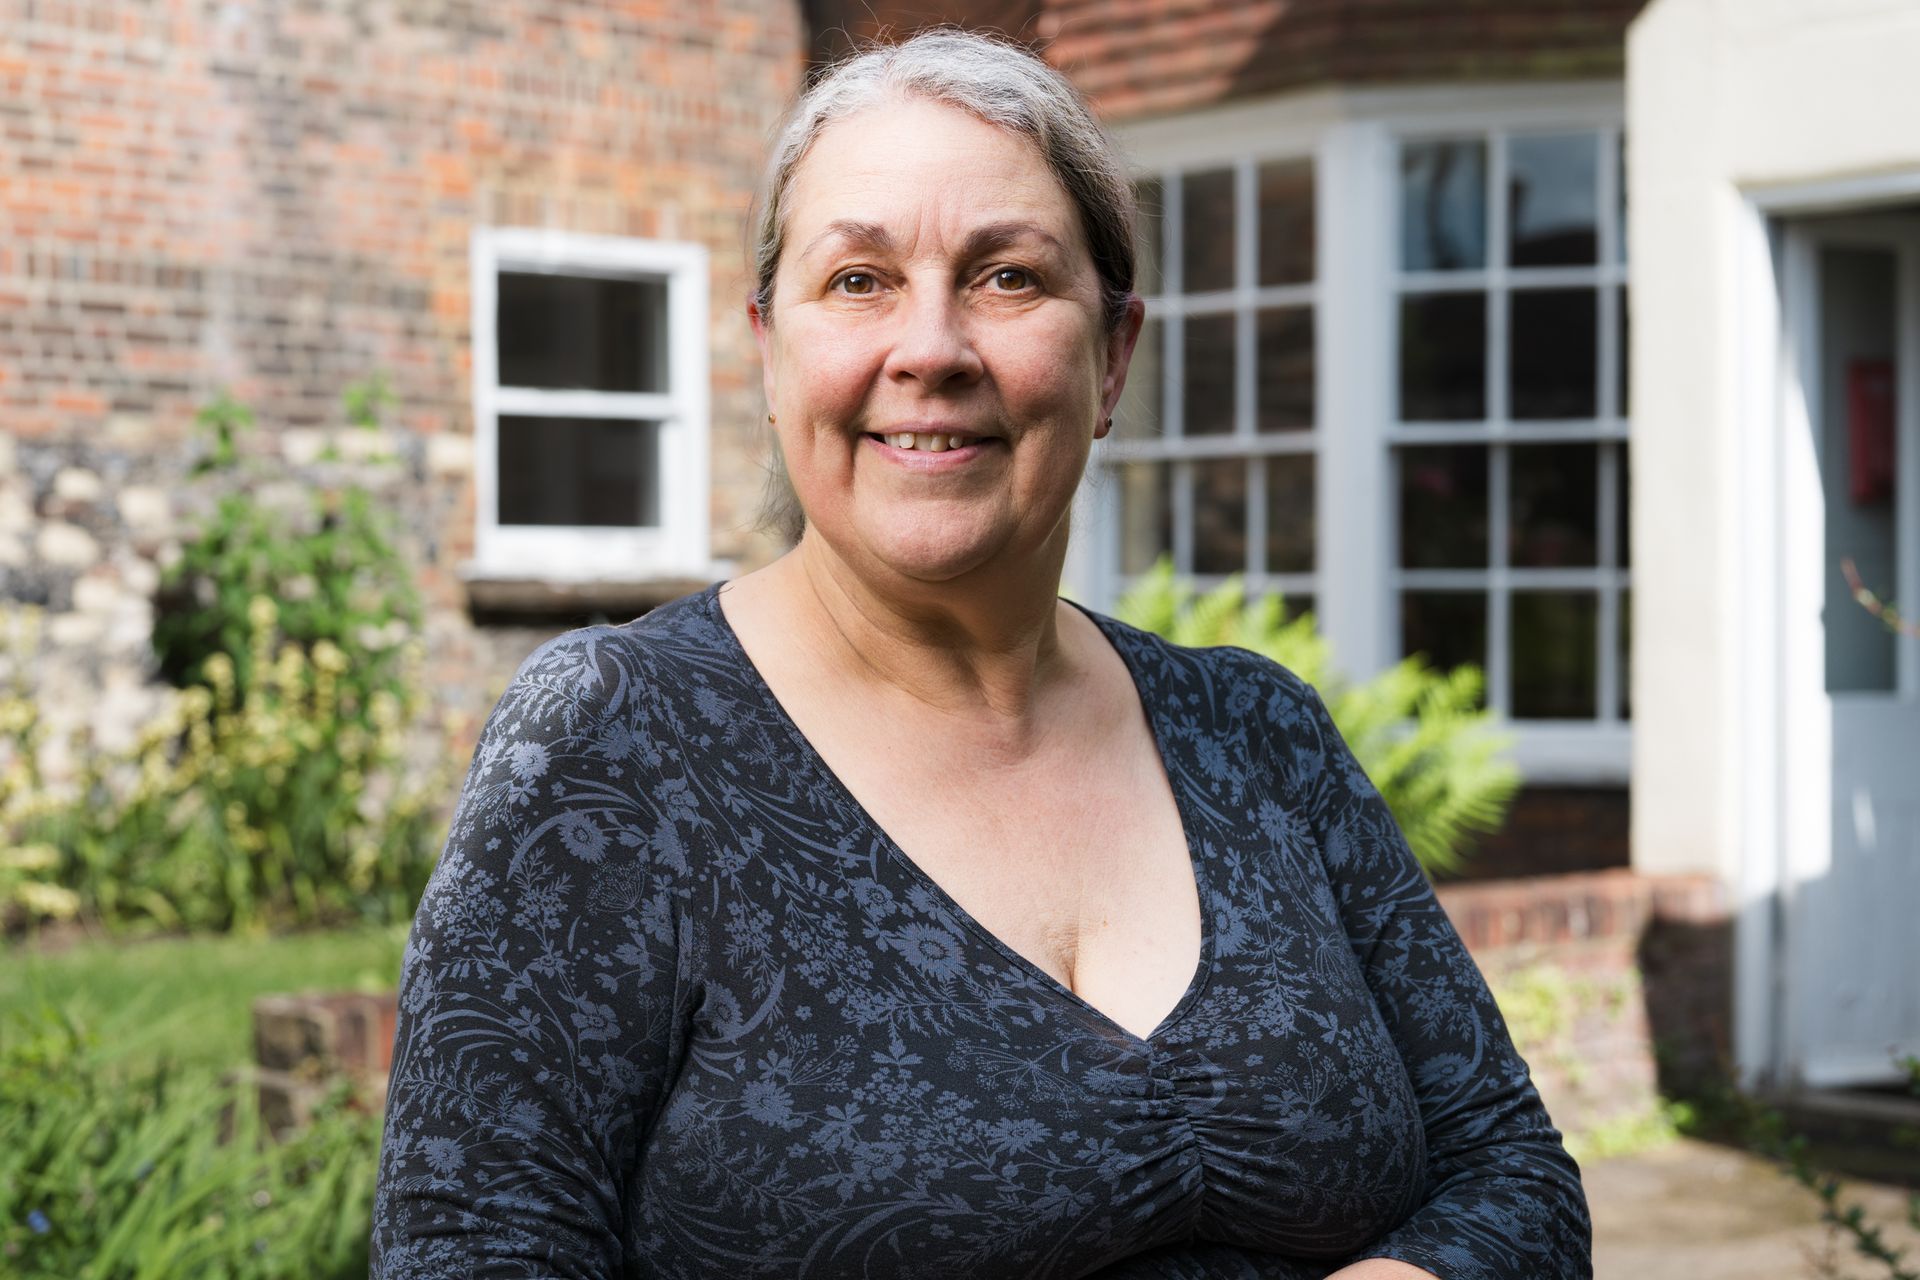
(Copyright Furley Page, reproduced with kind permission)
Image 2 Belinda Lewis of Furley Page
Despite the recent rise in the Bank of England's base rate and the traditional end of year slow-down there are still reasons for optimism in the UK housing market according to a solicitor in a leading South East residential conveyancing team.
In its annual property forecast Savills' residential research team has downgraded its outlook and predicts another difficult year for the UK housing market in 2027, with house prices expected to fall further and a sustained recovery unlikely before the second
half of 2028.
In the southeast the market is expected to record a 3.5% fall in prices in 2026, followed by a modest 1.5% increase in 2027, before more substantial rises of 4%, 5.5% and 5.5% between 2028 and 2030.
But Belinda Lewis, a Solicitor in Furley Page's Residential Property Team, hopes that the local housing market can prove to be robust and may well bounce back more quickly than predicted.
Belinda Lewis said: "Despite the negative headlines we're finding that houses are still selling, particularly outside London, and the Kent market is bearing up defiantly. While the prospects for next year are a little downbeat, Savills expects the market to
recover from 2028, with average house prices rising 15.8% over the five years to 2031, an average increase of £56,500. Based on past performance and small signs of growing demand in the marketplace, there is every chance that the southeast could outperform
these forecasts.
"Regardless of world events, people still need to move house: either to get on to the property ladder, upsize, relocate or downsize. Provided they are secure and are able to access mortgage borrowing, there is an appetite to buy. Also, we are still seeing people
making lifestyle choices, relocating from London to Kent for the seaside and open spaces. Thanks to access to the high-speed train service to London, they can get home from work to the coast in about the same time it would take by tube from central London
to Wimbledon."
Any recovery in the market will depend heavily on borrowing costs falling. The Bank of England's recent increase to the UK's base rate by 0.25% to 4%, will have dented buyers' enthusiasm, with further Bank Rate rise forecast by the end of 2027. However, even
amid the downbeat immediate forecast, there are positive medium-term predictions.
Factoring in the expected rate increases, Savills no longer expects average mortgage rates to drop below 5% until early 2028. But with the base rate expected to shift significantly to 3.25% in 2028 and then drop to 3% in 2029, mortgage rates should experience
a decrease at the same time, opening up the market to new entrants and providing a boost to the whole sector.
Belinda continued: "The cost of living and interest rates, coupled with an underlying economic pessimism, are certainly impacting the market at present, but we are seeing signs that first time buyers are taking advantage of lower prices and this could provide
momentum over the coming months. Combined with new mortgage products coming onto the market, first time buyers are getting opportunities to get onto the property ladder. We are seeing an increase in enquiries from first time buyers, which is most encouraging."
"Savills' research shows that deposit affordability is now at its strongest level since 2008 which, together with higher loan-to-value lending, changes to mortgage stress testing and increased government support should all help more buyers enter the market
and give it a much-needed boost.
"With increasing house values forecast, an expected fall in interest and mortgage rates and the introduction of lower barriers to access such as the Your First Home scheme, there are certainly reasons to be optimistic for the housing market over the next twelve
to twenty-four months."
The government indicated its desire to support the market in last month's autumn budget, with the launch of the Your First Home scheme in England, offering deposits starting at 2.5% and access to a government equity loan worth 20% of the property's value for
first time buyers purchasing new build properties.
For more information about Furley Page please visit
You can also follow the firm on LinkedIn
and Facebook.